Is a Leaking Skylight Covered by Insurance? What to Document
MEGA MEGA • October 28, 2026
Learn how cause, policy language, wear, and storm damage affect a skylight leak review, plus safe steps and a practical documentation checklist.
If you are asking whether a leaking skylight is covered by insurance, the cause of the water intrusion is usually one of the first issues to examine. A sudden opening caused by a covered storm event may be treated differently from water that enters through worn seals, deteriorated flashing, or a condition that developed over time. Your policy wording, the facts of the loss, and the insurer’s review control the outcome.
Ask about a skylight roof concern
This guide explains what to document, how to protect your home safely, and what questions to ask. It is general information, not a coverage determination, legal advice, or a promise that a claim will be approved. A roofing professional can describe visible roof conditions and repair options, but only your insurer can decide coverage under your policy.
What usually determines whether a leaking skylight is covered?
Insurance coverage is not decided by the presence of a ceiling stain alone. The insurer may consider the reported cause, the policy’s covered perils, exclusions, endorsements, duties after a loss, deductible, limits, and the available evidence. The same visible symptom can lead to different coverage questions depending on how and when the water entered.
For example, wind or hail may damage surrounding shingles, flashing, or the skylight assembly and create an opening. That situation may be evaluated differently from a seal that has gradually deteriorated. A long-running leak can also raise questions about repeated seepage, neglect, maintenance, or whether damage continued after the homeowner first noticed it. Do not assume that one factor decides the entire claim; ask how the policy applies to the specific facts.
Read the declarations page and the sections addressing dwelling coverage, covered causes of loss, exclusions, additional coverages, duties after a loss, and loss settlement. If a provision is unclear, ask the insurer to explain it in writing. The Texas Department of Insurance guidance on water damage and mold explains that coverage can depend on the source and cause of the water damage. It is useful background, but it does not replace your policy or your insurer’s decision.
Possible situation | Useful facts to record | Coverage question to ask
Sudden wind or hail damage — Date, weather, visible exterior damage, interior water marks — Does the policy cover this event and resulting damage?
Worn seal or deteriorated flashing — Condition, repair history, when symptoms first appeared — How do wear, deterioration, or maintenance exclusions apply?
Repeated or gradual seepage — Timeline, recurring stains, prior reports, earlier repairs — How does the policy address ongoing or repeated leakage?
Unclear or mixed cause — Photos, timeline, inspection observations, claim communications — What additional inspection or evidence is needed?
Interior damage after a roof opening — Affected ceilings, walls, flooring, belongings, and cleanup — Which resulting losses, if any, are addressed separately?
How do sudden damage and gradual wear differ?
It helps to separate the event that may have started water entry from the damage that appeared afterward. A storm might coincide with a leak, but timing alone does not establish the exact path or cause. For instance, rain can expose an older flashing problem; a wind event can move a roof component; or water may enter at a different roof feature and travel before showing near the skylight. Record the sequence without choosing among those explanations until the condition has been examined.
Consider three practical examples. In the first, a homeowner sees a new ceiling drip after hail and notices fresh damage on nearby shingles from the ground. The useful record includes the date, the new drip, the visible shingle condition, and photos. In the second, a faint brown ring has appeared several times over months, then becomes wet during ordinary rain. The timeline should show both the recurring mark and the new active leak. In the third, a storm is followed by a stain, but there is no safe view of the exterior. The homeowner can report the timing and request an inspection without stating that the storm broke the skylight.
These examples do not predict coverage. They show why two leaks that look alike indoors may require different questions about the policy. The insurer may distinguish damage to the roof opening from damage to interior finishes, and may evaluate each part under applicable policy terms. Ask the adjuster to explain any separate findings rather than assuming that a decision about one component answers every question about the loss.
For a clearer account, make a two-column note: “What I observed” and “What I do not know yet.” Observed facts might include water at the upper corner of a room, a stain that predates the storm, or a drip that began during heavy rain. Unknowns might include the entry point, the age of a failed seal, or whether a specific roof component was damaged. This simple distinction keeps your report accurate and gives an inspector useful questions to investigate.
A storm can affect more than the glass. Wind may lift or damage shingles near the skylight, shift flashing, or expose a joint. Hail can leave marks or damage components that are not obvious from inside the home. If water appears soon after a storm, note the date and conditions, but do not state that the storm caused the leak unless the evidence supports that conclusion.
Gradual wear presents a different set of questions. Seal failure, cracked materials, corrosion, failed flashing, or an installation detail that has allowed water in repeatedly may have developed over weeks, months, or years. A water mark tells you where water became visible, not necessarily where it entered or when the problem began. Water can travel along framing, insulation, or finished surfaces before appearing around the skylight.
Prior knowledge can also matter to the review. If you noticed bubbling paint, discoloration, dampness, or a recurring drip before the latest rain, record that accurately. Do not hide an earlier symptom, but do not guess at dates you cannot establish. A simple timeline separating what you observed from what you think may have caused it is more useful than an overconfident diagnosis.
Total Roof’s skylight leak repair guide provides a separate overview of common leak sources and safe first steps. You can also review the guide to a leak around a skylight to understand why water may appear inside away from the actual entry point. Neither a symptom nor an online guide proves what your policy covers.
What should you do when water is coming in?
Act first to protect people and limit additional damage. Insurance policies commonly include duties after a loss, but the exact requirements vary. Use the following order as a practical starting point and follow any instructions from your insurer.
- Protect people. Keep away from sagging ceiling materials, loose trim, and wet electrical fixtures. If water is near wiring, lights, outlets, or electrical equipment, do not touch the wet area. Contact an appropriate qualified professional or emergency services when there is an immediate safety risk.
- Protect belongings if it is safe. Move furniture, electronics, and valuables away from active drips. Place a container under a leak only when doing so does not require standing beneath an unstable ceiling or reaching into an unsafe area.
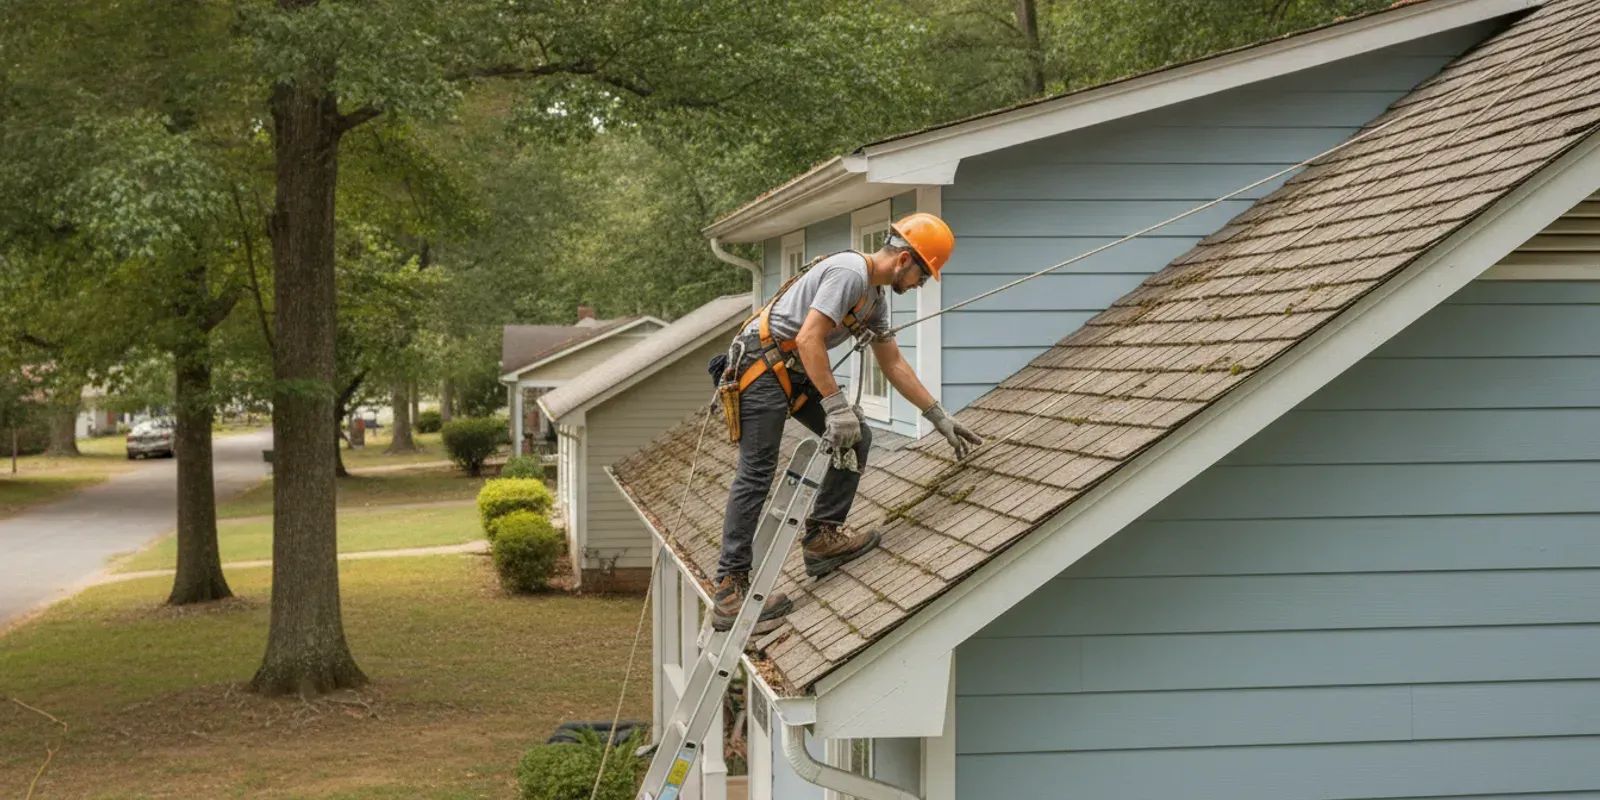
- Limit further interior damage. Use reasonable temporary measures that do not put you on a wet or steep roof. Do not climb outside to inspect a skylight during rain, wind, lightning, or other unsafe conditions. A tarp or exterior repair should be handled safely by a qualified person.
- Record the condition. Take wide and close photos from a safe location. Photograph the skylight, ceiling, walls, flooring, nearby furnishings, damaged belongings, and any exterior condition visible from the ground. Keep original files and note when they were taken.
- Notify the insurer promptly. Ask how to report the loss, whether an adjuster or inspection is needed, and what temporary work is allowed. Write down the claim number, dates, names, and instructions.
- Keep damaged items when practical. Do not discard materials or permanently alter the area before checking whether the insurer needs to inspect it, unless immediate action is necessary for safety or to prevent more damage. Photograph first when possible.
For a broader roof leak response, see Total Roof’s roof leak repair guide. It can help you organize immediate concerns without treating a general checklist as a substitute for professional safety judgment.
What documentation can help with a skylight claim?
A useful record is organized so another person can follow it without having been present. Create a simple event log with the date, weather as you experienced it, what you noticed inside, what action you took, and who you contacted. If you are unsure of a date, mark it as approximate. A sequence such as “small stain noticed sometime in early September; active drip after rain on October 24; insurer contacted October 25” is more reliable than trying to make every event sound tied to one day.
Keep separate folders for condition evidence and claim communications. Condition evidence includes original photos, video, repair records, and inspection notes. Claim communications include the policy documents, claim number, emails, letters, forms, estimates, and call notes. Name digital files with the date and room or view, such as “2026-10-25-bedroom-wide.jpg.” Avoid deleting the original file after creating a cropped copy.
When taking photos, start with context. Photograph the entire room and the skylight from a safe position, then capture the water mark, wet surface, and damaged property more closely. If a ruler or other reference is available, it can help show the scale of a stain, but do not touch wet wiring, climb furniture, or disturb unstable materials to improve a picture. If water changes over time, take another photo and label the time rather than overwriting the earlier image.
Make a checklist of items that may be relevant, but do not delay urgent protection while trying to complete it:
- Timeline: Write down when you first noticed water, when rain or a storm occurred, whether the leak stopped, and whether it returned. Separate dates you know from dates you are estimating.
- Photos and video: Capture the room from several angles, then take closer images of stains, wet materials, peeling paint, damaged belongings, and the skylight area. Include a reference such as the room layout so individual close-ups have context.
- Weather observations: Record what you personally saw or heard, such as heavy rain, hail, or strong wind. Avoid claiming that a weather event damaged the roof unless an inspection supports that conclusion.
- Prior history: Note earlier repairs, maintenance, recurring stains, prior leaks, or changes to the skylight. Include invoices, contractor reports, and correspondence you already have.
- Temporary protection: Keep receipts for emergency supplies, water removal, protective materials, cleanup, or temporary work. Ask the insurer what it wants before nonessential work begins.
- Claim communication: Save the policy, claim number, emails, forms, inspection notices, estimates, and notes from phone calls. Record the date, person, and main instruction after each conversation.
- Professional observations: Request an itemized description of visible conditions, recommended work, and inspection limits. A report should distinguish observed facts from conclusions that require additional access or testing.
Label files with dates and preserve original photos. Avoid editing an image in a way that removes context. If emergency work is necessary, photograph the area before work when safe, document what was done, and ask for an itemized invoice explaining the temporary measure.
How should you describe the problem to the insurer?
Use plain, factual language. A useful first report might be: “After rain on Tuesday, I noticed water at the inside edge of the skylight. I do not know when the leak began. I have photos of the room and would like to know the next steps.” That statement identifies an observation without presenting an unconfirmed cause as fact.
Ask practical questions rather than arguing for a result before the inspection. Consider asking:
- What is the deadline or preferred process for reporting this loss?
- Should I arrange an inspection before repairs beyond temporary protection?
- Which photos, estimates, receipts, and prior repair records do you need?
- What should I do with damaged materials and personal belongings?
- How will the deductible, limits, exclusions, and any applicable endorsements be explained?
- Can you provide the coverage decision and its basis in writing?
- What review, reconsideration, or appeal process is available if I disagree?
A contractor can inspect accessible areas, describe conditions, and explain repair choices. The contractor cannot decide whether your insurance policy covers the work. The insurer evaluates the claim under its contract. If you disagree with a decision, review the written explanation and policy, ask the insurer about its process, and consider contacting your state insurance department or a qualified adviser for guidance.
What if the skylight needs repair before the claim is resolved?
There can be a real tension between preserving evidence and stopping additional damage. A roof opening that allows more water inside may require prompt temporary protection. Contact the insurer as soon as practical and ask whether it wants photographs, an adjuster visit, or an inspection before permanent work. If waiting would create a safety hazard or allow additional damage, take reasonable emergency action and document why it was needed.
Keep temporary and permanent work separate in writing. Temporary work might protect an opening or catch active water. Permanent work may involve replacing a skylight, repairing flashing, replacing shingles, or restoring interior finishes. Ask for an estimate that identifies each scope instead of combining every item into one unexplained total.
Do not assume that an estimate equals an insurance determination. Similarly, do not assume that an insurer’s initial estimate identifies every repair a roof professional may recommend. If the two documents differ, provide both through the insurer’s process and ask what additional information could resolve the difference. Total Roof’s steps for addressing a leaking skylight offer repair-planning context, while its guide to finding a roof leak explains why locating an entry point can require care.
How can you compare repair recommendations?
A written comparison can also help keep repair planning distinct from the claim decision. Set up a short table or note with four headings: observed condition, work proposed, area included, and item still uncertain. For example, one proposal might identify loose flashing and recommend resetting or replacing it; another might recommend removing the skylight and replacing the surrounding materials. Those scopes may address different conditions, so ask each provider what evidence supports the recommendation and what work is conditional on opening the roof.
Check whether each document accounts for access, protection, removal, disposal, replacement materials, flashing details, nearby shingles, and any interior repairs. Ask whether the estimate includes temporary measures or only permanent work. If there is a line item you do not understand, request a plain explanation of what it covers. If an item is omitted because it cannot be seen yet, ask how that uncertainty will be handled if the work reveals additional damage.
Keep dated versions of estimates as they change. A revised document should make clear what changed and why. This is useful when an insurer asks for more information or when you compare the proposed work with an adjuster’s estimate. Do not treat different totals as proof that either party is wrong; first check whether the documents describe the same repair, materials, and affected areas.
When two recommendations do not match, first determine whether they inspected the same areas. One person may have viewed the interior and accessible roof surface, while another may have included flashing, surrounding shingles, decking, insulation, or interior finishes. A difference in scope is not automatically a contradiction.
Ask each provider to identify the confirmed condition, the proposed remedy, and any limitations. Useful questions include: Is the skylight itself damaged, or is water entering around the flashing? Does the recommendation include removal and disposal? Are surrounding shingles or underlayment included? Is interior drywall or paint part of the estimate? What temporary protection is required? Which items cannot be confirmed until materials are opened?
Compare scope rather than price alone. Two estimates may have different totals because one includes only a small flashing repair while another includes removal, replacement, disposal, and interior restoration. A written comparison helps you communicate with the insurer and decide what questions still need answers.
If you need to discuss a roof concern with Total Roof, you can review residential roof repair services or see roofing project examples. A discussion of repair needs is not a promise of insurance coverage, claim approval, or a particular repair outcome.
How can you stay organized from first leak to repair?
A simple sequence can prevent details from getting lost when the leak is stressful. On the first day, protect people and belongings if safe, photograph what is visible, write down when you noticed it, and report it to the insurer. Save the claim number and ask what they need next. If you arrange emergency protection, keep its receipt and a short note explaining why it could not wait.
Before an inspection, gather the policy, event log, relevant prior repair paperwork, photos, and any temporary-work invoice. Put questions in writing so you remember them during the visit. Examples include: “Can you tell whether the water entered at the skylight or nearby roof area?” “What parts were visible, and what parts could not be inspected?” and “Do you need photographs or another estimate before permanent work?” Do not pressure an inspector to confirm a cause that has not been established.
After the inspection, write down what you understood and ask for any key instructions or decision in writing. If the insurer requests additional documentation, note the request and response date. When a repair is completed, keep the final scope, invoice, and photographs of the work when available. A compact file lets you answer later questions without relying on memory, especially if the leak appeared more than once.
For homeowners in the area, Total Roof’s Henry County roof repair information and Georgia roofing services page are available as starting points for learning about repair options. These resources describe roofing services; they do not determine insurance coverage.
What mistakes can make the process harder?
Many claim problems begin with rushed assumptions rather than a single bad decision. Avoid these common missteps:
- Calling a cause certain before inspection: Saying “the storm did it” or “the skylight failed from age” may go beyond what you know. Describe the timing and visible facts instead.
- Waiting while water continues to enter: Delayed action can increase interior damage. Report the issue and ask about safe temporary measures.
- Making permanent repairs before documenting: Replacement may remove evidence the insurer wants to review. Photograph first and coordinate when practical.
- Throwing away damaged property too soon: Keep items and packaging when safe and practical, or document them carefully before disposal.
- Relying on a verbal summary alone: Save written instructions and ask for a written coverage explanation if the claim decision is disputed.
- Comparing totals without comparing scope: A lower estimate may omit flashing, disposal, interior work, or temporary protection.
- Ignoring safety: Do not enter a wet electrical area or climb onto a slick roof to gather evidence.
These precautions are not tactics for forcing approval. They are ways to create an accurate record, reduce preventable damage, and keep communication clear.
Frequently asked questions
Does homeowners insurance cover every skylight leak?
No. Coverage depends on the cause, policy terms, exclusions, endorsements, timing, and the insurer’s review. A leak by itself does not establish that the loss is covered.
Will a storm-related skylight leak automatically be approved?
No. A storm may be relevant, but the insurer still evaluates the policy and evidence. Record when the storm occurred, what you observed, and any visible damage, then ask what inspection or documentation is needed.
Should I repair the skylight before an adjuster visits?
Take safe photos and contact the insurer first when practical. If temporary action is necessary to protect people or prevent additional damage, document the condition and work, keep receipts, and ask how permanent repairs should be handled.
Can a roofer tell me whether my claim will be covered?
A roofer can describe accessible conditions and repair options, but only the insurer can determine coverage under your policy. Keep the repair assessment and coverage decision as separate parts of your records.
What if the leak appeared before the latest storm?
Tell the insurer what you know, including earlier stains, drips, or repairs. Do not guess about the start date. A complete timeline helps the insurer evaluate whether the latest event, an earlier condition, or more than one factor is involved.
Contact Total Roof about a skylight leak
Careful documentation, prompt reporting, and safe temporary protection can make the next steps clearer, but your policy and insurer’s decision determine whether a particular skylight loss is covered.